Hawaiʻi Homebuyers Have a New Credit Score Option: What VantageScore 4.0 Could Mean for Your Mortgage
For decades, one name has dominated credit scoring when it comes to getting a conventional mortgage: FICO.
That is beginning to change.
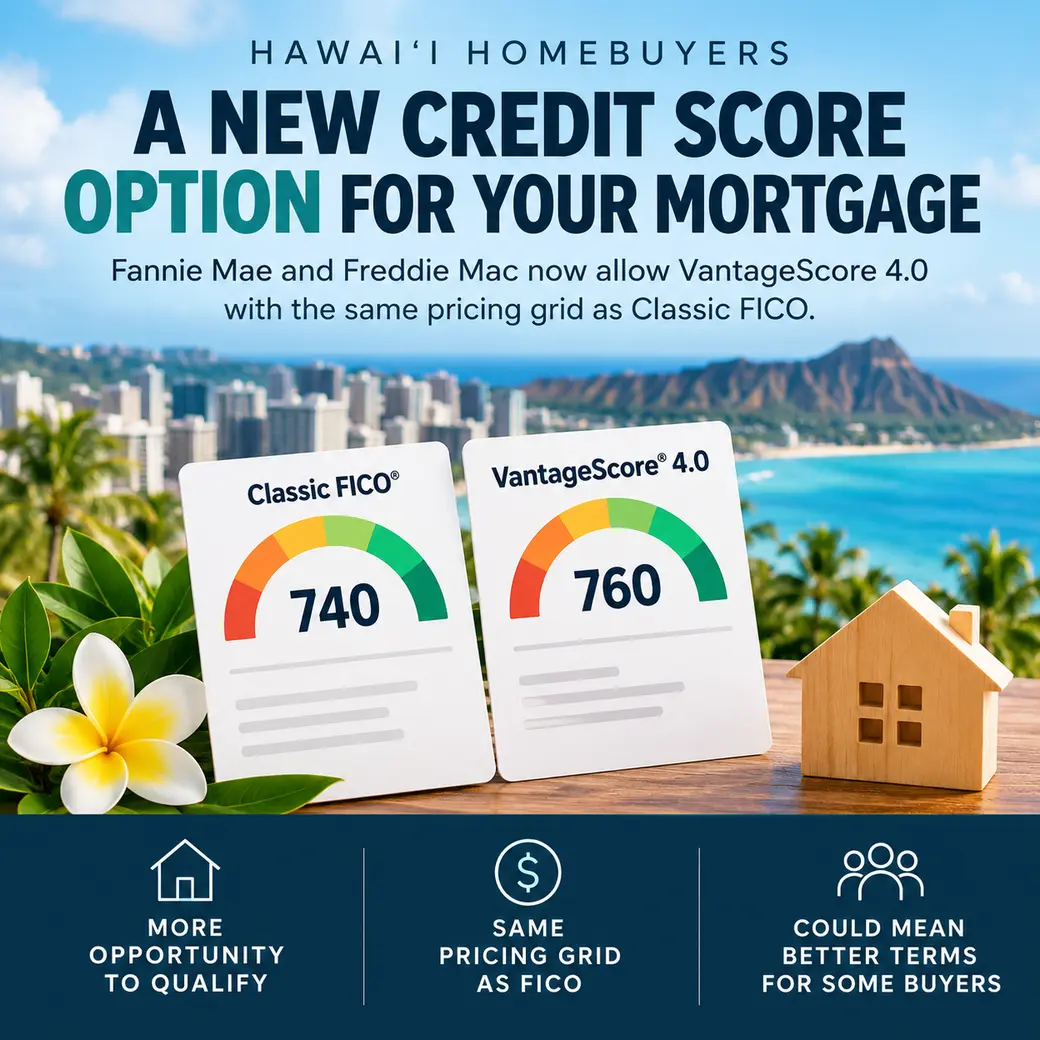
The Federal Housing Finance Agency (FHFA) has expanded the use of VantageScore 4.0 for mortgages purchased by Fannie Mae and Freddie Mac. And on September 29, 2026, another important development was announced: mortgages using VantageScore 4.0 and Classic FICO will now be subject to the same loan-level pricing grid.
For some Hawaiʻi homebuyers, this could make a meaningful difference.
What Changed?
Earlier this month, Fannie Mae and Freddie Mac expanded VantageScore 4.0 availability to all of their approved lenders for eligible loans. Lenders may now use either Classic FICO or VantageScore 4.0 when originating and selling qualifying conventional mortgages.
FHFA confirms that Classic FICO remains an approved option. It isn't disappearing overnight. Instead, lenders now have another approved credit-scoring model available to them.
The latest change concerns how those scores affect mortgage pricing.
Initially, VantageScore 4.0 was subject to a 20-point downward adjustment when determining certain loan-level price adjustments, or LLPAs. FHFA has now moved Fannie Mae and Freddie Mac to one pricing grid for both Classic FICO and VantageScore 4.0, eliminating that 20-point adjustment.
In simple terms, VantageScore 4.0 is no longer being placed on a separate pricing track simply because a different scoring model was used.
Why Could This Matter to a Homebuyer?
Your credit score can affect much more than whether you're approved for a mortgage.
Depending on the loan, your score can influence your interest rate, loan-level pricing adjustments and ultimately how much cash you need to bring to closing.
Here's where the new system becomes interesting: your VantageScore 4.0 and Classic FICO scores may not be the same.
VantageScore 4.0 is a newer scoring model that evaluates credit differently from the Classic FICO models traditionally used in mortgage lending. FHFA notes that newer credit-scoring models can incorporate additional information, including rental payment history, in assessing credit risk.
That doesn't mean everyone's VantageScore will be higher. But for certain borrowers, the difference could be significant.
Some Borrowers Are Already Seeing a Difference
Early lender results are worth watching.
According to HousingWire, United Wholesale Mortgage reported that approximately 25% of its borrowers were seeing a more advantageous credit result using VantageScore 4.0 compared with Classic FICO.
Rocket Mortgage has also tested the models extensively. The company reported testing VantageScore against approximately 1.4 million credit reports and found that the newer model helped some additional borrowers qualify for mortgages.
Even more interesting, Rocket reported that among borrowers who received better mortgage pricing because of VantageScore, the average savings was approximately $1,600 at closing.
Those numbers shouldn't be interpreted as a guarantee. Every borrower's credit profile is different, and a VantageScore will not necessarily be higher or result in better loan terms.
But it does demonstrate why having more than one scoring model available could matter.
What Does This Mean for Hawaiʻi Buyers?
Hawaiʻi's high home prices can magnify relatively small differences in mortgage qualification and pricing.
A difference in a credit score could potentially affect the pricing adjustment associated with a loan. And for a borrower who is near a particular underwriting or pricing threshold, having another approved credit-scoring model available could potentially make a difference.
This is especially important for buyers who may have previously assumed that their credit score automatically prevented them from qualifying for conventional financing.
It may be worth taking another look.
Should You Ask Your Lender About VantageScore 4.0?
Yes.
If you're preparing to purchase a home in Hawaiʻi, particularly if credit has been an issue in the past, consider asking your lender:
“Do you offer VantageScore 4.0 for Fannie Mae or Freddie Mac loans, and have you compared how I qualify under VantageScore 4.0 versus Classic FICO?”
Not every borrower will benefit from the newer scoring model, and the lender ultimately has to determine which programs and scoring options are available for your particular loan.
But it's certainly worth asking the question.
FICO Isn't Going Away Yet
One important clarification: this does not mean FICO has been eliminated from mortgage lending.
FHFA says lenders may currently choose between Classic FICO and VantageScore 4.0 for eligible loans sold to Fannie Mae and Freddie Mac. Classic FICO remains an approved scoring model, and no retirement date has been announced.
FICO 10T, another newer scoring model approved by FHFA, is also expected to become available for Fannie Mae and Freddie Mac loan deliveries at a later date.
What we're seeing is not the immediate replacement of FICO. We're seeing the beginning of something the mortgage industry hasn't had for decades: meaningful competition between credit-scoring models.
The Bottom Line
For Hawaiʻi homebuyers, the biggest takeaway is simple: the credit score you've known may no longer be the only score that matters when applying for a conventional mortgage.
If you've considered purchasing a home but were concerned that your credit score might prevent you from qualifying—or result in unfavorable mortgage pricing—it may be worth having another conversation with a knowledgeable lender.
VantageScore 4.0 won't improve the situation for every borrower. But for some buyers, a different way of evaluating credit could potentially mean better mortgage pricing or even the difference between qualifying and not qualifying.
And in Hawaiʻi's housing market, every additional financing option is worth understanding.
Our local expertise can help point you in the right direction for a new mortgage. It's always a good time to buy a home in Hawai'i.
This article is provided for general informational purposes only and is not mortgage, lending, financial, tax or legal advice. Mortgage eligibility, credit scoring and loan pricing depend on individual circumstances and lender requirements.
Sources: Federal Housing Finance Agency (FHFA), Fannie Mae, Freddie Mac and HousingWire.
My Hawaiʻi Real Estate by ZT Hawaiʻi LLC
Experience Hawaiʻi Real Estate. Elevated.
Categories
Recent Posts